Kenya’s mortgage market is showing renewed growth, with lower average interest rates, larger loans and longer repayment periods helping more buyers finance property purchases. However, affordability remains a major hurdle for households seeking to own homes.
Kenya’s residential real estate market is entering 2026 with renewed activity in mortgage financing, offering fresh opportunities for homebuyers, property developers and investors. The latest banking sector figures point to a recovery in lending for property purchases, following a contraction in 2024.
According to the Central Bank of Kenya (CBK), the value of outstanding mortgage loans increased by 10 per cent to KSh307.2 billion in December 2025, up from KSh279.3 billion a year earlier. The KSh27.9 billion increase marked the strongest annual expansion in a decade, according to reporting on the regulator’s annual report.
The recovery suggests that financing conditions are becoming more supportive of property ownership. Nevertheless, the expansion of mortgage lending does not necessarily mean that homeownership is now affordable for the majority of Kenyans.
Lower Mortgage Interest Rates Offer Some Relief
The average mortgage interest rate declined from 15.2 per cent in 2024 to 13.5 per cent in 2025. This reduction lowered borrowing costs for some prospective homeowners and helped support the growth of housing finance.
Mortgage rates varied considerably across lenders, ranging from 7.5 per cent to 19.6 per cent during 2025. This difference highlights the importance of comparing financing terms before committing to a home purchase.
The impact of interest rates is particularly significant in Kenya, where many households must balance housing costs against school fees, food, transport and other living expenses. Even a modest reduction in the cost of borrowing can make a difference to a household considering a mortgage.
However, the advertised interest rate is only one part of the equation. Buyers must also consider deposit requirements, loan-related charges, insurance, property taxes where applicable and the full repayment period.
Read Also: The Screen-Free Childhood: How Gated Community Design Changes How Kids Grow Up
Bigger Loans Reflect the Rising Cost of Property
The average mortgage size increased by 11.1 per cent, rising from KSh9 million in 2024 to KSh10 million in 2025.
This growth indicates that borrowers are taking on larger loans to finance property purchases. It may reflect higher property prices, the purchase of more expensive homes or changes in the types of properties being financed.
The number of outstanding mortgage accounts increased more slowly, from 30,016 to 30,762, representing growth of approximately 2.5 per cent. The figures suggest that the expansion in mortgage value was driven substantially by the size of loans rather than a comparable increase in the number of borrowers.
For Kenya’s property market, this distinction matters. An increase in the total value of mortgages does not automatically translate into widespread access to homeownership.
Many middle-income earners and first-time buyers continue to face the challenge of raising deposits and meeting lenders’ income requirements. Those with irregular earnings may encounter additional difficulties proving that they can sustain monthly repayments.
Longer Repayment Periods Help Spread the Cost
Banks extended the average mortgage repayment period from 11.1 years in 2024 to 11.5 years in 2025.
Longer repayment periods can reduce monthly instalments, potentially making a property purchase more manageable for qualifying borrowers. However, extending a loan can also increase the total interest paid over its lifetime.
For example, a buyer considering a KSh10 million mortgage should not assess affordability based solely on the property’s purchase price. The monthly repayment, the stability of household income and the ability to maintain an emergency fund are equally important.
Borrowers should also establish whether their loans carry fixed or variable interest rates. A fixed-rate arrangement can provide greater certainty over repayments during the agreed period, while a variable-rate facility may expose the borrower to changes in lending costs.
The objective should be to secure financing that remains affordable throughout the loan term rather than simply qualifying for the largest amount a bank is willing to lend.
Read Also: Who Pays When a Water Pipe Bursts Under a Shared Access Road in Kenya?
Affordable Housing Could Expand the Market
The CBK expects mortgage demand to increase in 2026, supported by interest-rate stabilisation and a larger supply of affordable housing through government-backed projects.
Affordable housing has the potential to connect more households to formal home financing, particularly if developers produce units that match the incomes of their intended buyers.
For this to happen, housing supply must be accompanied by appropriate financing arrangements. A home described as affordable may still be beyond a buyer’s reach if the required deposit is too high or monthly instalments exceed the household’s repayment capacity.
Developers and financial institutions therefore have an important role in aligning property prices, loan terms and household incomes.
Partnerships between banks and property developers could also help prospective buyers access financing packages linked to specific residential developments.
Mortgage Refinancing Could Support Further Growth
The Kenya Mortgage Refinance Company (KMRC) is another institution relevant to the development of housing finance.
The CBK reported that ten lending institutions had outstanding mortgage refinancing facilities from KMRC in 2025, up from seven in 2024. Their outstanding facilities increased from KSh11.9 billion to KSh19.6 billion.
Mortgage refinancing helps participating financial institutions access longer-term funding, potentially improving their ability to provide housing loans.
If these arrangements continue expanding, they could support the availability of longer-term home financing. The eventual benefit to borrowers will depend on how lenders translate funding advantages into loan pricing, repayment periods and eligibility requirements.
Digitisation of land transactions could also help reduce delays in property purchases and mortgage disbursements, although improvements in processing alone cannot resolve the underlying affordability challenge.
What the Mortgage Recovery Means for Residential Real Estate
The renewed growth in mortgage lending has implications across Kenya’s residential real estate sector.
For property developers, stronger mortgage activity may broaden the pool of potential buyers, provided their units fall within borrowers’ financial reach. Developers who understand their target market’s purchasing power may be better positioned to structure projects around actual demand.
For homebuyers, improved financing conditions create an opportunity to compare mortgage products and assess whether buying a home is financially sustainable. Prospective buyers should obtain clear information about deposits, interest rates, fees and the consequences of missed payments before signing a financing agreement.
For investors, the recovery provides useful information about housing finance conditions, but it should not be treated as proof that property prices will rise everywhere. Location, infrastructure, rental demand, construction quality and the availability of employment opportunities remain important considerations when evaluating a residential property.
The growth in mortgage lending also presents an opportunity for the industry to address the gap between housing supply and effective demand. Producing more homes is important, but ensuring that intended buyers can finance them is equally necessary.
Read Also: What Happens to Your Plot If the Seller Is Married? Spousal Consent and Land Sales in Kenya
Will Mortgage Growth Make Homeownership More Accessible?
Kenya’s mortgage market has recorded measurable progress, with outstanding loans reaching KSh307.2 billion by the end of 2025. Lower average interest rates, larger mortgage facilities and longer repayment periods helped support that expansion.
The challenge for 2026 is to convert this growth into broader access to homeownership. That will require continued attention to borrowing costs, household incomes, deposit requirements and the supply of appropriately priced homes.
For buyers exploring residential real estate in Kenya, the changing mortgage environment makes it worthwhile to assess available financing options alongside the location, price and long-term value of a property.
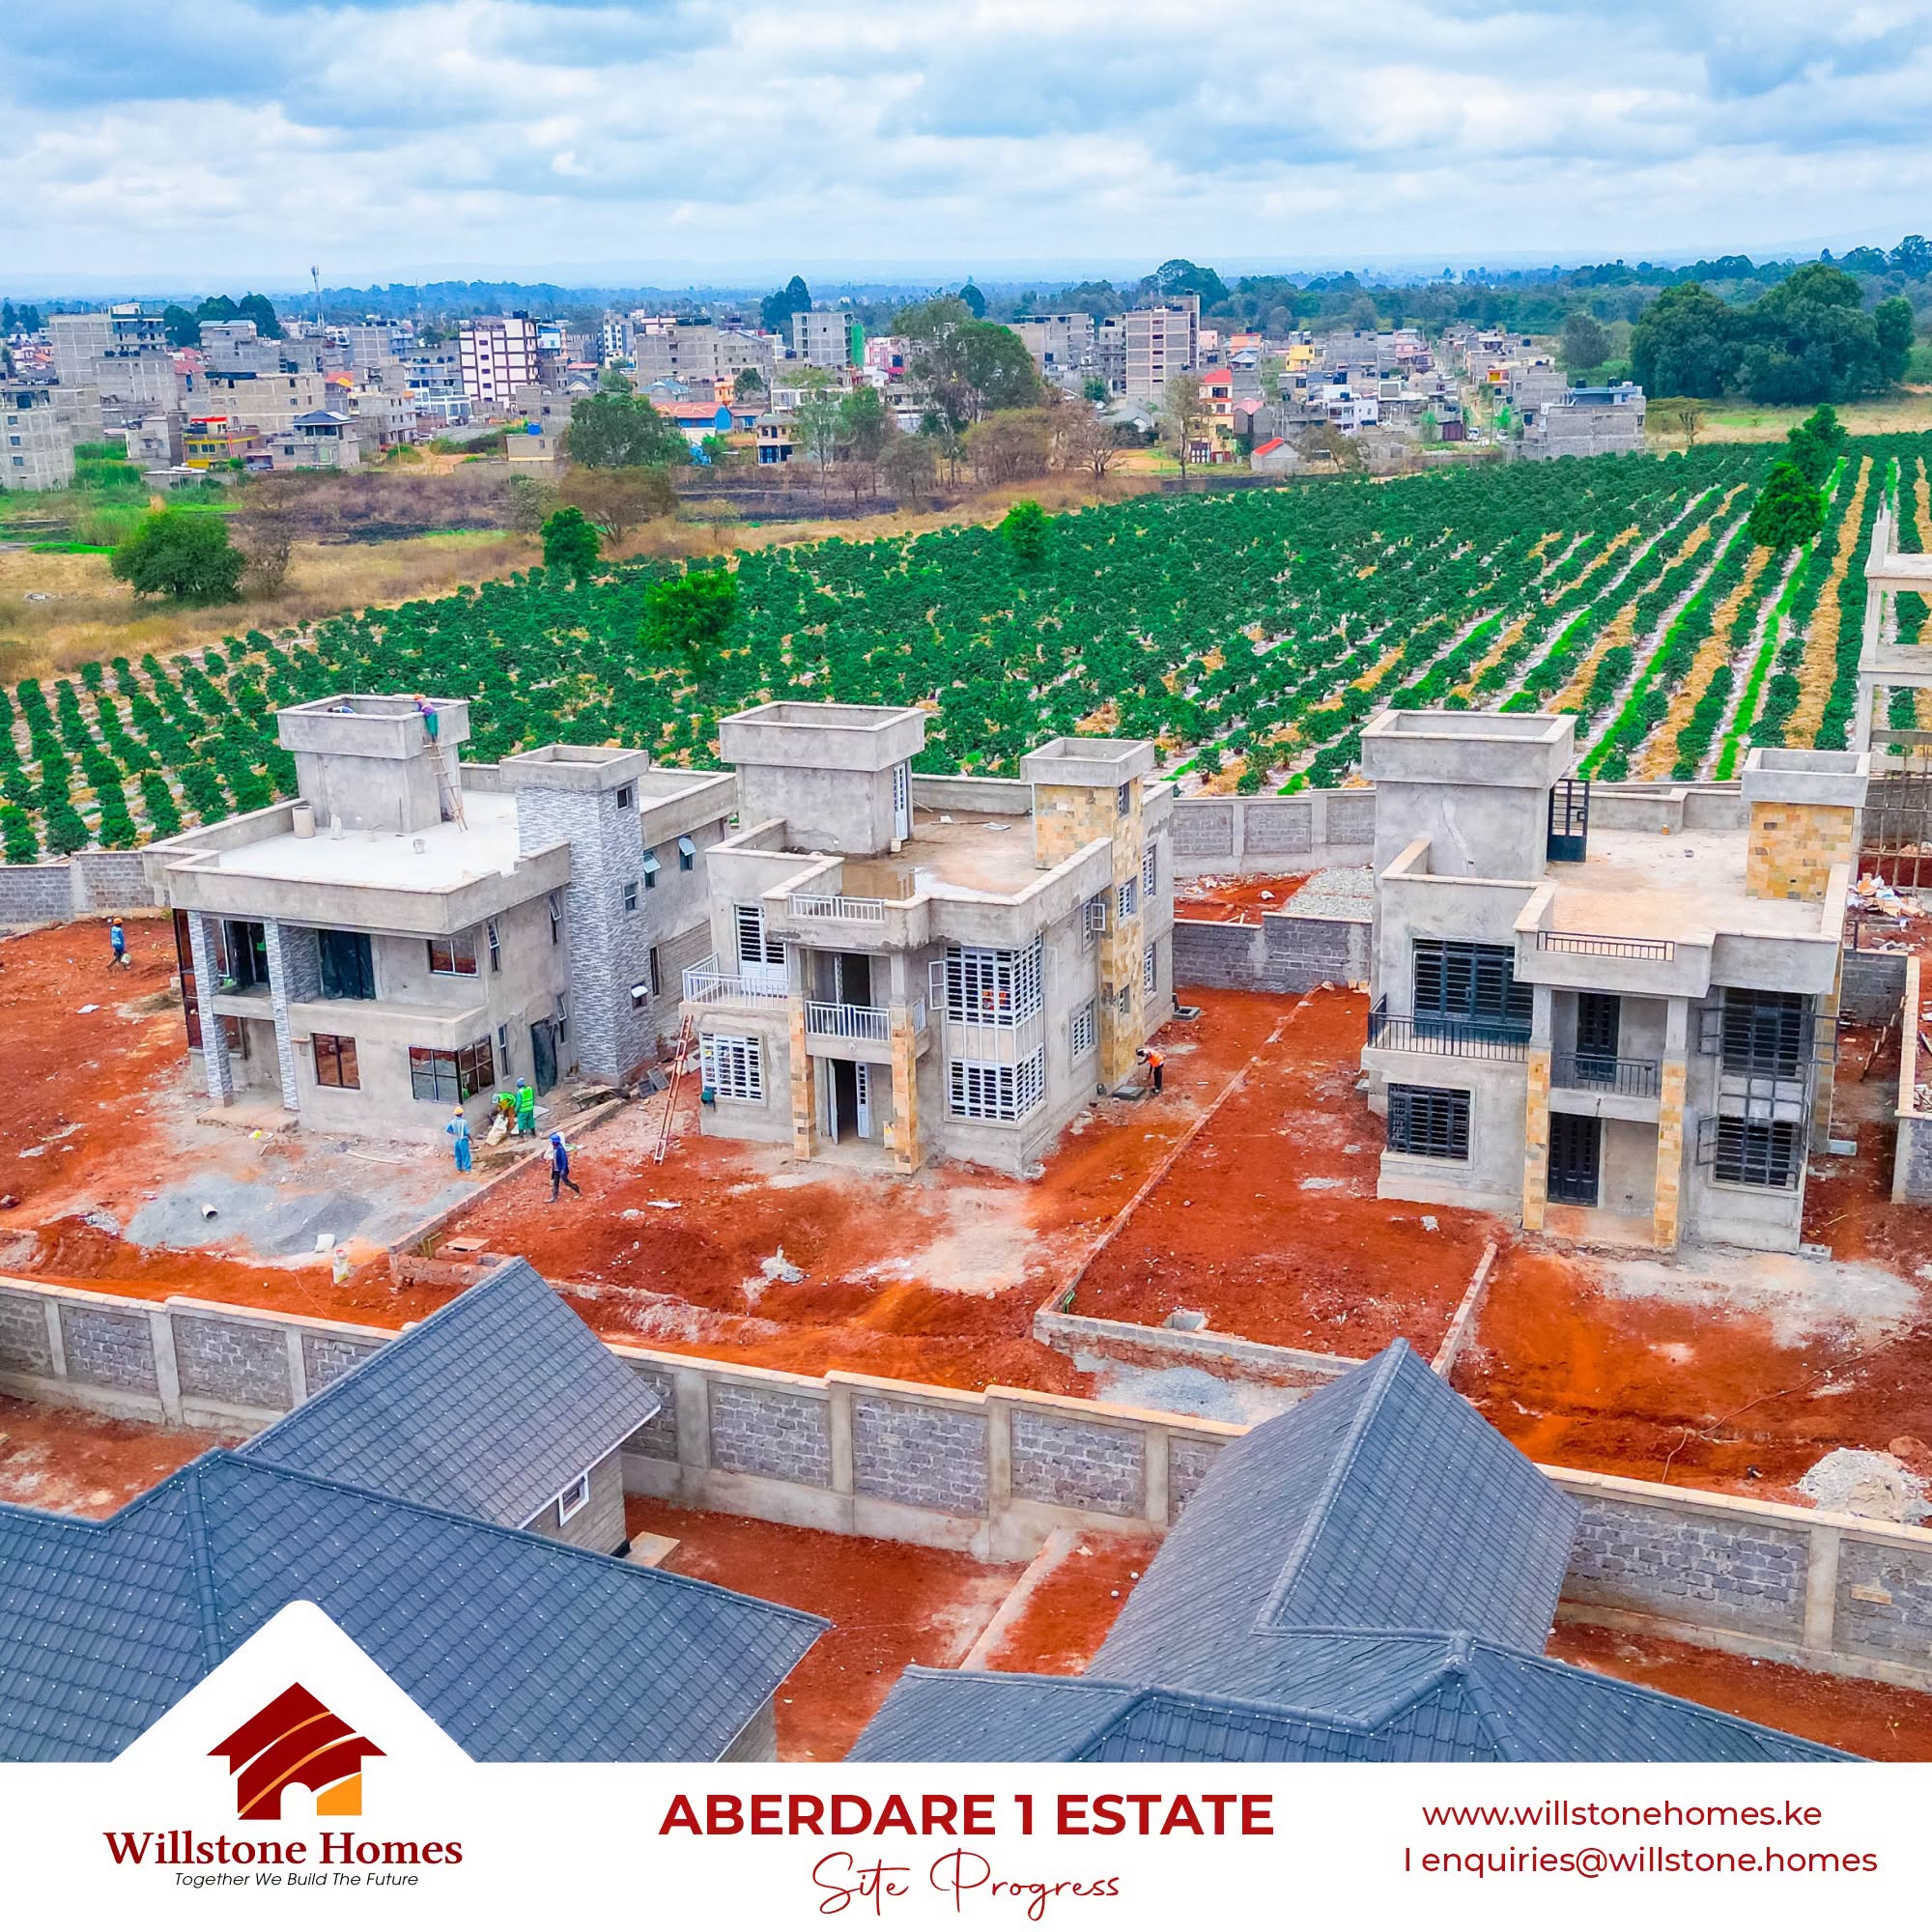
At Willstone Homes, prospective buyers can explore property opportunities in Nairobi and Kiambu, including developments along growing residential corridors. As with any property purchase, buyers should evaluate the location, total acquisition cost, infrastructure, legal documentation and suitability of the property for their financial circumstances before making a commitment.
Ultimately, a growing mortgage market can support Kenya’s real estate industry, but sustainable homeownership will depend on whether financing and property prices become accessible to a wider section of the population.
Read Also: How Dangote’s KSh 2 Trillion Refinery Could Transform Kenya’s Real Estate Market