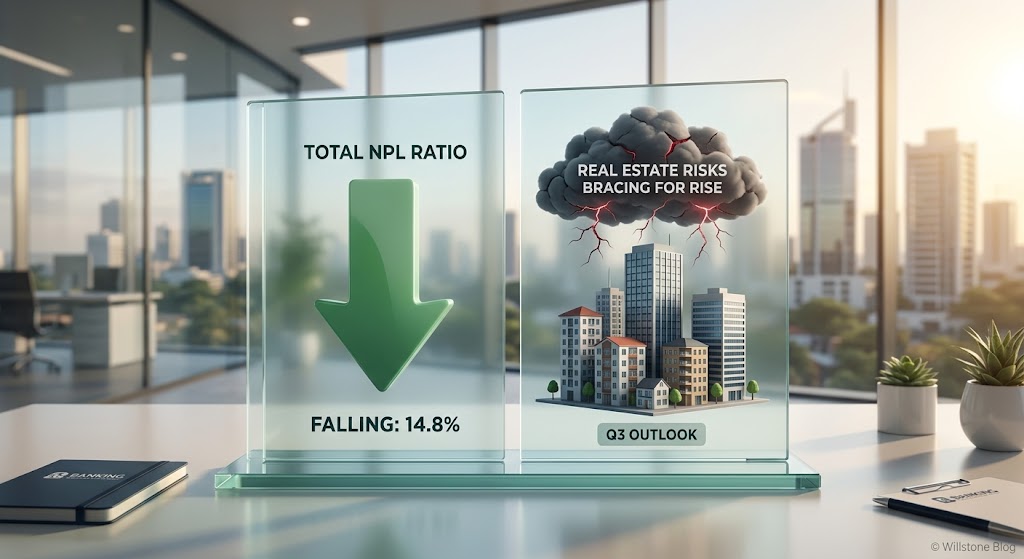
The share of commercial banks in Kenya expecting non-performing loans (NPLs) in the real estate sector to rise over the coming quarter nearly doubled in the second quarter of 2026—climbing to 27% in June from 14% in March. The sharp shift, detailed in the Central Bank of Kenya’s (CBK) latest Credit Officer Survey Report, highlights growing caution among credit risk teams despite broader improvements in headline banking sector metrics.
While banks continued expanding their overall loan books, property financing has emerged as the sector credit officers are monitoring with the highest degree of vigilance—alongside a booming household loan book that is driving both robust credit demand and the most aggressive recovery operations in the banking industry.
Key Takeaways: CBK Q2 2026 Credit Survey
- Real Estate Stress: 27% of banks expect real estate bad loans to increase in Q3, up from 14% in Q1.
- Statistical Illusion in NPLs: Headline NPL ratio dropped from 15.6% to 14.8%, but 78% of the improvement was driven by new loan growth (+4.3% to KSh 4.65T) rather than debt recovery (bad loans fell just 1.3%).
- Consumer & Trade Engine: Trade (65%) and Personal/Household (66%) credit experienced the highest surges in borrower demand.
- Aggressive Recoveries: 81% of lenders plan to intensify debt recovery on personal loans in Q3—the highest of any economic sector.
- Solvency Safeguards: Total bank assets grew to KSh 8.88 trillion, with capital adequacy holding strong at 20.0% (well above the 14.5% statutory threshold).
Read Also: How the Conveyancing Process Really Works When Buying Property in Kenya
1. Headline NPL Drop: Growth Over Debt Recovery
On the surface, Kenya’s banking sector showed health during the second quarter. The gross non-performing loan ratio dropped to 14.8% in June from 15.6% in March.
However, a closer look at the underlying balance sheets reveals that this statistical relief was largely a denominator effect. Total gross loans expanded 4.3% to KSh 4.65 trillion, diluting the overall ratio, while the actual volume of bad loans contracted by a modest 1.3%.
 Gross NPL Ratio Movement (Q1 vs Q2 2026)
 ┌─────────────────────────────────────────────────────────────┐
 │ Q1 (March): 15.6%  █████████████████████████████████        │
 │ Q2 (June):  14.8%  █████████████████████████████            │
 └─────────────────────────────────────────────────────────────┘
  *Driven primarily by a +4.3% surge in total credit issue (KSh 4.65T)
   rather than actual default repayments (-1.3%).
Because actual default resolution remains slow, banks remain skeptical that credit quality has genuinely turned a corner:
- 55% of surveyed banks expect overall sector NPLs to remain flat or increase in Q3 2026.
- Only 45% of credit officers anticipate a genuine reduction in non-performing debt over the next three months.
2. Sectoral Divergence: Where Credit is Flowing
Trade financing and personal/household lending absorbed the lion’s share of commercial bank appetite for new lending in Q2 2026, largely driven by corporate working-capital demands and cost-of-living household bridge financing.
| Economic Sector | Increased Credit Demand (June vs March) | Expected NPL Outlook (Q3 Expectation) | Bank Credit Policy / Recovery Focus |
| Trade | 65% (up from 62%) | 39% Expect Decline | 29% Expect Increase | Easiest Access: 29% eased terms (highest across all sectors). |
| Personal & Household | 66% (up from 58%) | 43% Expect Decline | 35% Expect Increase | Hardest Recovery: 81% of banks intensifying collection efforts. |
| Building & Construction | 42% (up from 29%) | 41% Expect Decline | 22% Expect Increase | Improving Outlook: High optimism on project loan servicing. |
| Real Estate | Divergent | 27% Expect Increase (up from 14%) | Heightened Vigilance: Selective underwriting on long-term structures. |
| Transport & Communication | 32% (down from 35%) | 37% Expect Decline | 18% Expect Increase | Softening Demand: Asset performance stabilizing. |
| Agriculture | Stable | 16% Expect Increase (up from 11%) | Weather & input cost sensitivity keeping risk elevated. |
| Energy & Water | Stable | 19% Expect Increase (up from 14%) | Infrastructure delays impacting utility cash flows. |
| Manufacturing | Stable | 21% Expect Increase (flat) | High operational overheads maintaining baseline default risk. |
| Financial Services | Stable | 34% Expect Decline | 13% Expect Increase | Most stable sector: 53% expect NPLs to hold steady. |
3. Real Estate vs. Construction: A Tale of Two Timelines
One of the most striking insights in the June 2026 CBK report is the sharp split in sentiment between Building & Construction and Real Estate development.
- Building & Construction (Upstream Optimism): Credit demand jumped significantly to 42% in June (from 29% in March). 41% of lenders expect NPLs in construction to decline—one of the most optimistic readings in the entire survey. This suggests ongoing contractor pay-offs, government infrastructure disbursements, and active site works.
- Real Estate (Downstream Cashflow Pressure): Conversely, 27% of credit officers expect property loan defaults to climb in Q3. This highlights delayed off-take, slower secondary market sales, and stretched rental yield margins making long-term debt servicing harder for completed commercial and residential projects.
4. Household Debt: Record Demand Meets Aggressive Collections
Personal and household credit logged the highest demand of any sector in the economy, with 66% of banks noting increased loan applications. Lenders report that working-capital needs, inflationary pressures, and short-term liquidity deficits are driving consumers to digital loans, salary advances, and credit facilities.
However, banks are taking no chances with retail delinquency:
81% of commercial banks confirmed they will actively intensify debt recovery efforts in the personal and household segment during Q3 2026—up from 75% in March. This represents the most aggressive collection posture of any sector in Kenya’s financial landscape.
Read Also: Why Your Property Isn’t Selling: 6 Critical Checks Before You Slash the Price
5. Balance Sheet Strength and Capital Buffers
Despite the pockets of credit risk in property and retail lending, Kenyan banks are managing these risks from a position of comfortable liquidity and capital adequacy. Credit standards remained unchanged across all economic sectors in Q2, indicating that banks are maintaining steady risk parameters rather than panic-tightening.
Key Banking System Fundamentals (June 2026)
├── Total System Assets: KSh 8.88 Trillion (+1.7% QoQ)
├── Loans to Total Assets Ratio: 52.3% (up from 51.0%)
└── Capital Adequacy Ratio (CAR): 20.0% (vs 20.4% in March)
    └── Regulatory Minimum Threshold: 14.5% [Buffer: +5.5%]
The expansion in total assets to KSh 8.88 trillion and a higher loan-to-asset allocation (52.3%) show that commercial banks remain eager to intermediate capital. With a 20.0% Capital Adequacy Ratio, the banking sector holds a robust 5.5-percentage-point cushion over regulatory minimums—providing ample firepower to absorb potential real estate provisioning without threatening institutional solvency.
What This Means for Real Estate Buyers & Developers
- For Homebuyers & Mortgagors: With banks intensifying retail loan collections and keeping credit standards firm, prospective homebuyers should maintain clean credit profiles and leverage structured, low-risk mortgage models (such as KMRC-backed fixed-rate loans) to secure favorable long-term approvals.
- For Developers & Investors: Lenders are favoring completed, fast-yielding residential developments (like single-level suburban estates and affordable housing blocks) over speculative, high-density commercial developments where off-take risk remains elevated.
Read Also: Why You Should Visit an Off-Plan Property Site Before You Buy